

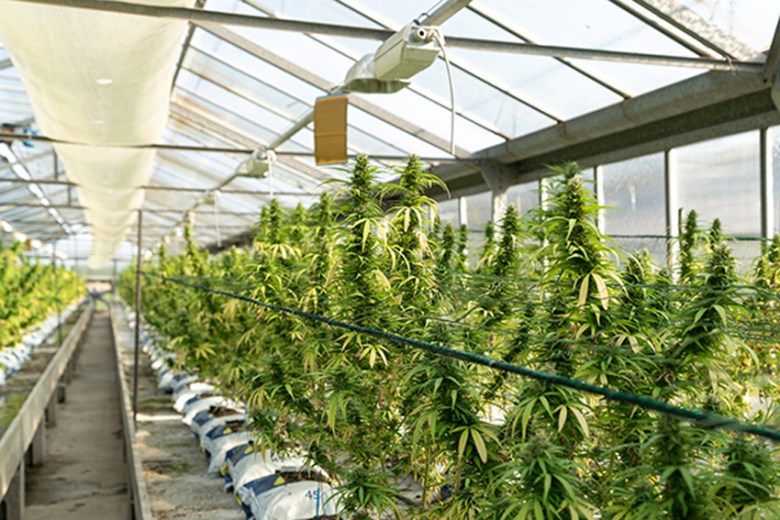
Connecticut is about to change the way it taxes cannabis, and the state’s own fiscal analysis says the change will reduce cannabis-tax revenue. The bigger question is whether that official estimate adequately accounts for what is happening in the market.
On Oct. 1, Connecticut’s cannabis tax framework changes under Public Act 26-68. The state is replacing its THC-based excise tax with a flat-rate 10.75% excise tax on cannabis gross receipts. The existing tax is calculated according to the labeled amount of THC in a product rather than its retail price.
The difference is not merely academic.
Using Connecticut’s reported cannabis tax collections and retail-sales data, the existing potency tax generated roughly $2.8 million to $3.4 million per month between January and May 2026. Applying the new 10.75% rate to the same period’s taxable retail sales produces substantially less revenue, roughly $1.9 million to $2.2 million per month. That represents an average monthly revenue shortfall of roughly $1 million under the new tax, assuming recent sales, product mix and prices remained otherwise unchanged.
That should not be confused with a $1 million monthly budget deficit. It is a counterfactual estimate of the difference between what Connecticut’s existing tax generated and what the new tax would have generated on the same underlying sales. But it illustrates the size of the revenue reset the state is about to undertake.
And there is another reason to pay attention: Connecticut’s cannabis prices have been falling.
Under the existing potency-based tax, a decline in the retail price of a particular product does not, by itself, reduce the tax collected on a given quantity of THC sold. Under the new system, however, the tax is directly tied to taxable gross receipts. If prices decline, the state will need sufficient growth in taxable sales volume to offset that decline.
Put simply, the new tax creates a different economic dependency. Maintaining cannabis-tax revenue will require enough growth in taxable gross receipts to compensate for the initial revenue disadvantage of the new rate and for any subsequent decline in prices.
The state’s own fiscal watchdog has already acknowledged an initial disadvantage.
The Office of Fiscal Analysis estimates that replacing the current cannabis tax with the 10.75% excise tax will reduce state revenue by $1.9 million in fiscal year 2027 and $2 million in fiscal year 2028. OFA projects the loss continuing at $2.1 million in fiscal year 2029 and approximately $2.2 million annually thereafter.

Those figures should be treated as a baseline, not the end of the analysis.
OFA’s published fiscal note does not disclose assumptions for future cannabis-price compression, sales-volume growth or the elasticity between the two. That distinction matters because the new tax base is gross receipts. If Connecticut’s cannabis prices continue to decline, the state will need additional taxable sales volume or other growth in gross receipts simply to prevent revenue from falling further.
There is an important wrinkle in where that loss will be felt.
The Social Equity and Innovation Account is not projected to take the initial hit. Public Act 26-68 temporarily increases the account’s share of cannabis-tax revenue from 65% to 70% for fiscal years 2027 and 2028, while reducing the General Fund’s share from 10% to 5%.
That change shields the Social Equity and Innovation Account from a net revenue loss in those first two fiscal years. But it does not eliminate the underlying problem. OFA projects that beginning in fiscal year 2029, the account will lose approximately $1.6 million annually, with the loss rising to about $1.7 million thereafter.
In other words, the legislature has temporarily changed the distribution formula to cushion the account. It has not eliminated the revenue problem.
Municipalities are treated differently. Public Act 26-68 leaves the 3% municipal cannabis tax unchanged, and OFA identifies no direct municipal fiscal impact from the state tax change.
But municipalities are not completely insulated from a weakening cannabis market. Their 3% tax is itself based on gross receipts. If Connecticut’s cannabis prices and taxable sales continue to decline, municipal collections would eventually be affected as well. The distinction is that the municipalities are insulated from the rate change, not necessarily from the market conditions that determine the size of their tax base.
This is precisely why the assumptions behind the state’s forecast deserve scrutiny.
My concern is not that Connecticut has necessarily miscalculated the future. It is that the public fiscal analysis does not tell us how much additional sales volume would be required to overcome falling prices and the lower tax yield produced by the new system.
That is a question the legislature should be able to answer before the new tax takes effect.
I raised the broader problem in a Jan. 26 Hartford Courant op-ed, writing that if Connecticut was serious about turning its “currently moribund cannabis industry into the significant revenue engine it was promised to be,” the state needed a “hard reset” and “a hopeful, holistic revisiting of cannabis regulation as a whole.”
The 2026 legislative session did change the tax structure. It also made other changes to cannabis policy. But it did not resolve many of the broader regulatory and market problems that must be addressed alongside any tax reform.
That leaves Connecticut with a particularly important policy experiment beginning Oct. 1.
The state is moving from a tax based on the amount of THC sold to a tax based on the amount of money consumers spend. If prices keep falling, the new system will require the market to generate enough additional taxable sales volume to make up the difference.
OFA has already estimated that the tax change itself will cost the state roughly $2 million a year.
The unanswered question is how much more the state could lose if the market does not grow fast enough to overcome continuing price compression.
That is not a prediction that Connecticut’s cannabis-tax revenues will collapse. It is a question that should have been modeled before the state changed the tax base.
If the goal of legalization was to create a sustainable legal cannabis market that could fund public priorities and equity initiatives, Connecticut should not wait until the revenue starts falling to discover whether the numbers work.
Lou Rinaldi lives in Guilford.