

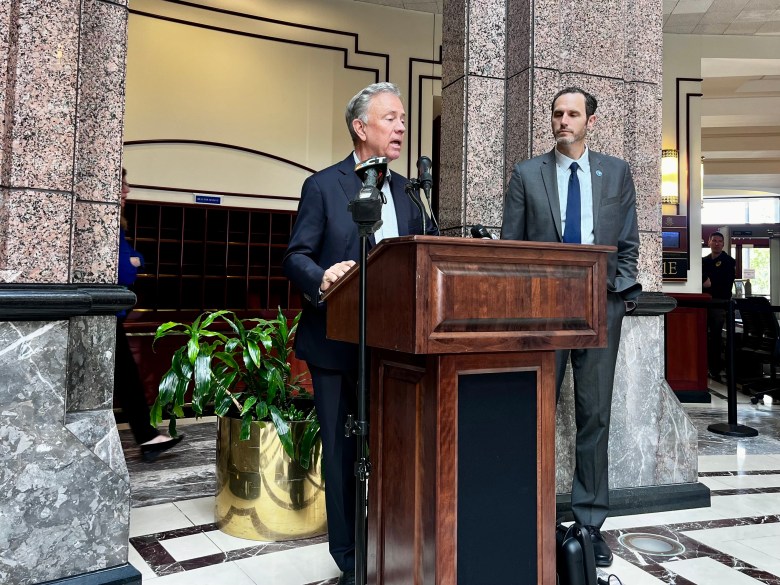
Gov. Ned Lamont put down a marker with more than 40,000 unionized state employees this week, reaching an “understanding” to extend valuable retirement benefits for at least one year in the next gubernatorial term.
The State Employees Bargaining Agent Coalition, which represents nearly all major employee unions in state government, notified rank-and-file members of the tentative understanding Thursday morning.
It’s one of the largest issues to face legislators and Connecticut’s governor in 2027.
But because no formal contract amendment has been negotiated to date and none is likely to be done until after the November elections, Lamont’s pledge is conditional on winning reelection this fall. He faces a challenge from Republican Sen. Ryan Fazio of Greenwich, who already has said he believes state employee benefits are too costly for taxpayers and need to be reformed.
“From opposite sides of the bargaining table, it is already clear the parties [union leaders and the Lamont administration] share an understanding of how important these benefits are to maintaining a strong, experienced public workforce,” SEBAC leaders wrote to rank-and-file union members.
The current contract, which guarantees state employees access to a pension and retirement healthcare once service requirements have been reached, expires June 30.
But unions leaders wrote “the parties have reached an agreement that no changes in pension or healthcare will occur before June 30, 2028, unless mutually agreed upon by both the state and SEBAC, adding more certainty for members. That should give plenty of time for employees to have all the information they need to make the best decisions about their future.”
The coalition limited its public comments about the announcement to the statement sent to its members.
Lamont’s budget director, Office of Policy and Management Secretary Josh Wojcik, wrote in an email to state agency heads that extending current benefits at least for one more year also would help ensure departments are properly staffed.
The state experienced a major surge in retirements in the first six months of 2022 as veteran workers scrambled to leave service before new limits on pensions took effect.
“This additional time will allow us to better evaluate and manage staffing needs across state agencies, properly plan for the implementation of any future changes and give employees the time and information they need to make informed decisions about retirement,” Wojcik wrote.
Fazio could not be reached for comment Thursday morning.
But House Minority Leader Vincent J. Candelora, R-North Branford, noted that governors traditionally don’t make such public pledges when overall negotiations are far from resolved, especially during a gubernatorial campaign.
“This circumvention of the traditional process to me is quite disturbing and suggests to me the governor is abusing his position for campaign purposes,” Candelora said. “It reeks of politics.”
Connecticut has been grappling with high state employee benefit costs for decades.
Most of that problem stems from poor savings habits by governors and legislators who served prior to 2011. According to a 2015 study from the Center for Retirement Research at Boston College, the state failed to properly save for more than seven decades. This deprived the state treasurer of huge assets that otherwise could have been invested to generate billions of dollars in revenue.
Unions helped to close state budget deficits by accepting concessions in 2009, 2011 and 2017, weakening retirement benefits and freezing wages.
Connecticut legislators enacted aggressive budget caps in 2017 that forced unprecedented surpluses. In the last seven years, Lamont and legislators have poured $11 billion in surplus into the pension funds.
But the state still carries more than $30 billion in unfunded pension liabilities, one of the largest burdens, per capita, in the nation, and isn’t expected to finish paying that off until well into the 2040s.
