

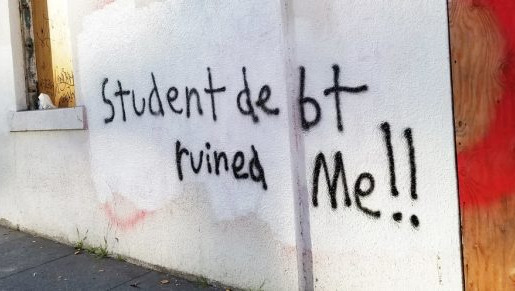
A student loan crisis is brewing in Connecticut, and recent federal policy changes are making it considerably worse.
The good news is that the state can still help residents before missed payments become defaults and those defaults lead to their wages and tax refunds being seized. Statewide guidance can help families secure relief before the damage deepens.
The governor’s office reported last month that approximately 521,400 Connecticut residents hold $19.8 billion in federal student debt. The state has the nation’s fifth-highest student loan average per person and an above-average delinquency rate. For families already juggling housing, groceries, and childcare, that debt adds pressure to budgets with little room to spare.
Consider Jon Coffin, a Bridgeport teacher who recently told Connecticut Public that he owed more than $160,000 in student loans. Despite keeping up with his monthly payments, he’s struggling to weigh everyday purchases for his family against his heavy student loan bill.
For borrowers who fall behind, the consequences are even more severe. Recent reports indicate that the federal government plans to start seizing wages and tax refunds from defaulted borrowers this winter.
For a Connecticut resident with $50,000 in student loans and a disposable income of $60,000, this will mean up to $11,000 in lost cash in 2027 through federal seizures. At scale, the federal government can use these tools to forcibly take an estimated $300 million next year from the 91,000 Connecticut residents who are already in default. That money will entirely disappear from the state’s economy.
Borrowers need reliable assistance as federal support weakens. With the most affordable federal income-driven repayment option (known as the SAVE plan) ending, borrowers must now choose a new repayment plan. Those who don’t will be moved into a standard repayment plan that will result in significantly higher payments for many. Meanwhile, the GAO found that the U.S. Department of Education’s Office of Federal Student Aid lost nearly half its staff during 2025. This attrition places borrowers at risk, as the agency is unable to assess the accuracy of loan servicer records and their call quality, which will increase the frequency of costly errors.
Having led both the Consumer Financial Protection Bureau and Federal Student Aid, I saw essential relief that existed only on paper without reaching borrowers in need. Federal benefits offer no real help if people cannot successfully claim them.
Income-driven repayment can lower payments for eligible borrowers. Public Service Loan Forgiveness offers another path for qualifying public servants and non-profit employees who can see their debt entirely eliminated. Borrowers in default need more help to understand how second-chance programs such as rehabilitation or consolidation can help them exit default. Each option involves paperwork, deadlines, and servicer processes that are intricate and easy to get wrong. Borrowers shouldn’t have to navigate them alone.
Gov. Ned Lamont and the legislature have established the Office of the Student Loan Ombudsperson. Michelle Jarvis-Lettman is a great resource to help borrowers and make sure they understand their rights. But even the best firefighters need reinforcements. Connecticut should give her office the tools and resources to match this crisis.
Connecticut’s next step should be a statewide service that helps residents secure relief. Working in coordination with the Ombudsperson, it should combine easy-to-use digital enrollment tools with qualified specialists who help borrowers complete applications for federal relief and resolve obstacles. A coordinated campaign among colleges, employers, unions and community organizations can effectively connect residents to the service, extending the office’s reach and impact.
Helping residents claim federal assistance also helps the state. Lower payments leave families more money for rent, food, and childcare —money that is spent on local businesses. Instead of Washington forcibly seizing up to $300 million next year from Connecticut borrowers, these federal programs ––when properly accessed–– can mitigate defaults and create hundreds of millions of dollars in savings to boost the local economy.
Connecticut has already recognized the problem and built a foundation for action. Now it can help residents claim the federal benefits they need and deserve before federal garnishments of wages and benefits put more household income at risk.
Richard Cordray served as the first director of the Consumer Financial Protection Bureau and later as chief of Federal Student Aid, overseeing the federal student loan program.