

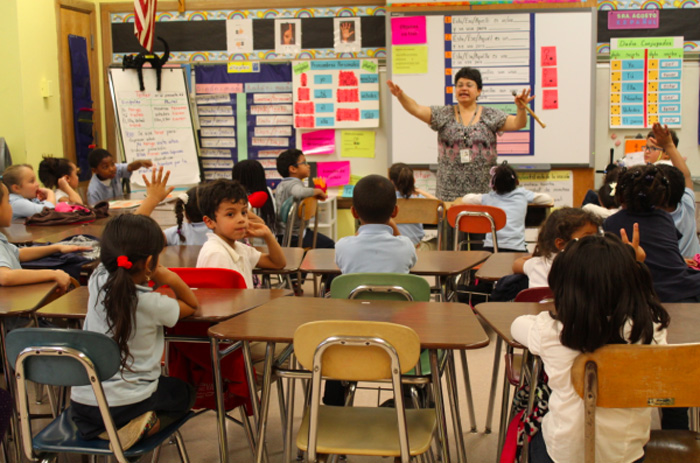
It seems everyone is talking about Nicole Hannah-Jones’ recent New York Times piece describing the educational experiences of her daughter, Najya, in the New York City public schools. If you haven’t read it, suffice to say that those experiences were less than ideal.
In recent days there have been dozens, if not hundreds, of commentaries on Hannah-Jones’ piece, and each one seems to have a different take on who is the villain in the story. Writing in the NY Post, Daniel di Martino insists that it is teacher’s unions. In the Free Press, Coleman Hughes suggests that an unwillingness to discipline disruptive children is a large part of the problem. In Slate, Jill Filipovic identifies no clear villain, but notes we need to make sure we are, ”not lowering the bar just because some students have a harder time clearing it.”
What all the commentators can agree on is that many, many schools in the United States are deeply dysfunctional. And, for this reason, many, many U.S. school children are receiving (as Hughes puts it in the Free Press), “[not just] a subpar education; they get no education, period.”
Fortunately, help is on the way. In 2025 the federal government created a provision that could put over $270 billion dollars every year into our educational system. The money would come from an optional tax credit (the Federal Scholarship Tax Credit) which, starting January 1, allows each U.S. citizen who owes at least $1,700 in taxes to (instead of paying tax) donate up to that amount to a scholarship granting organization (SGO) of his or her choice. Unlike a tax deduction, the credit means the donation is completely cost-free to the taxpayer.
The SGOs would take the money raised and use it to pay for educational expenses for children in their respective states. The term SGO is a misnomer, since the money disbursed need not be a scholarship in a traditional sense. It could be used for any “qualified elementary or secondary education expense” and could be given to both public and private school students. The law specifically allows expenses as diverse as books, technology, tutoring, extended day programs and special needs services.
Hannah-Jones’ article points out that disadvantaged school districts typically have less money available to them even though their student bodies have higher needs. This is primarily because public schools in the U.S. are mostly funded from local property tax receipts. Raising taxes is clearly not possible in poorer areas where citizens are already struggling to make ends meet. The new tax credit breaks down the correlation between local property tax revenues and resources available to schools, providing a new mechanism for monies to flow to under-resourced schools.
What is the catch, you ask? Only one. Any taxpayer is eligible to donate (again, at no cost to him or herself) to a qualified SGO. However, if you want your gift to go to help students in your state, your governor has to opt in to the program. If not, you can only donate to a scholarship granting organization in a state whose governor has opted in.
You would think it would be a no-brainer for states to opt-in. However, the IRS reports that as of October 13, 31 have done so and Connecticut is not one of them. SGOs need time to plan to handle the new donations that will be coming in.
Given the potential benefit to their neediest students, my only question is, “What is Connecticut waiting for?”
Christopher Rhoads is an associate professor in the Neag School of Education at the University of Connecticut. The views expressed here are his own and do not represent those of his institution.